
Diposting Pada: Feb 09, 2026 - 5 Dilihat
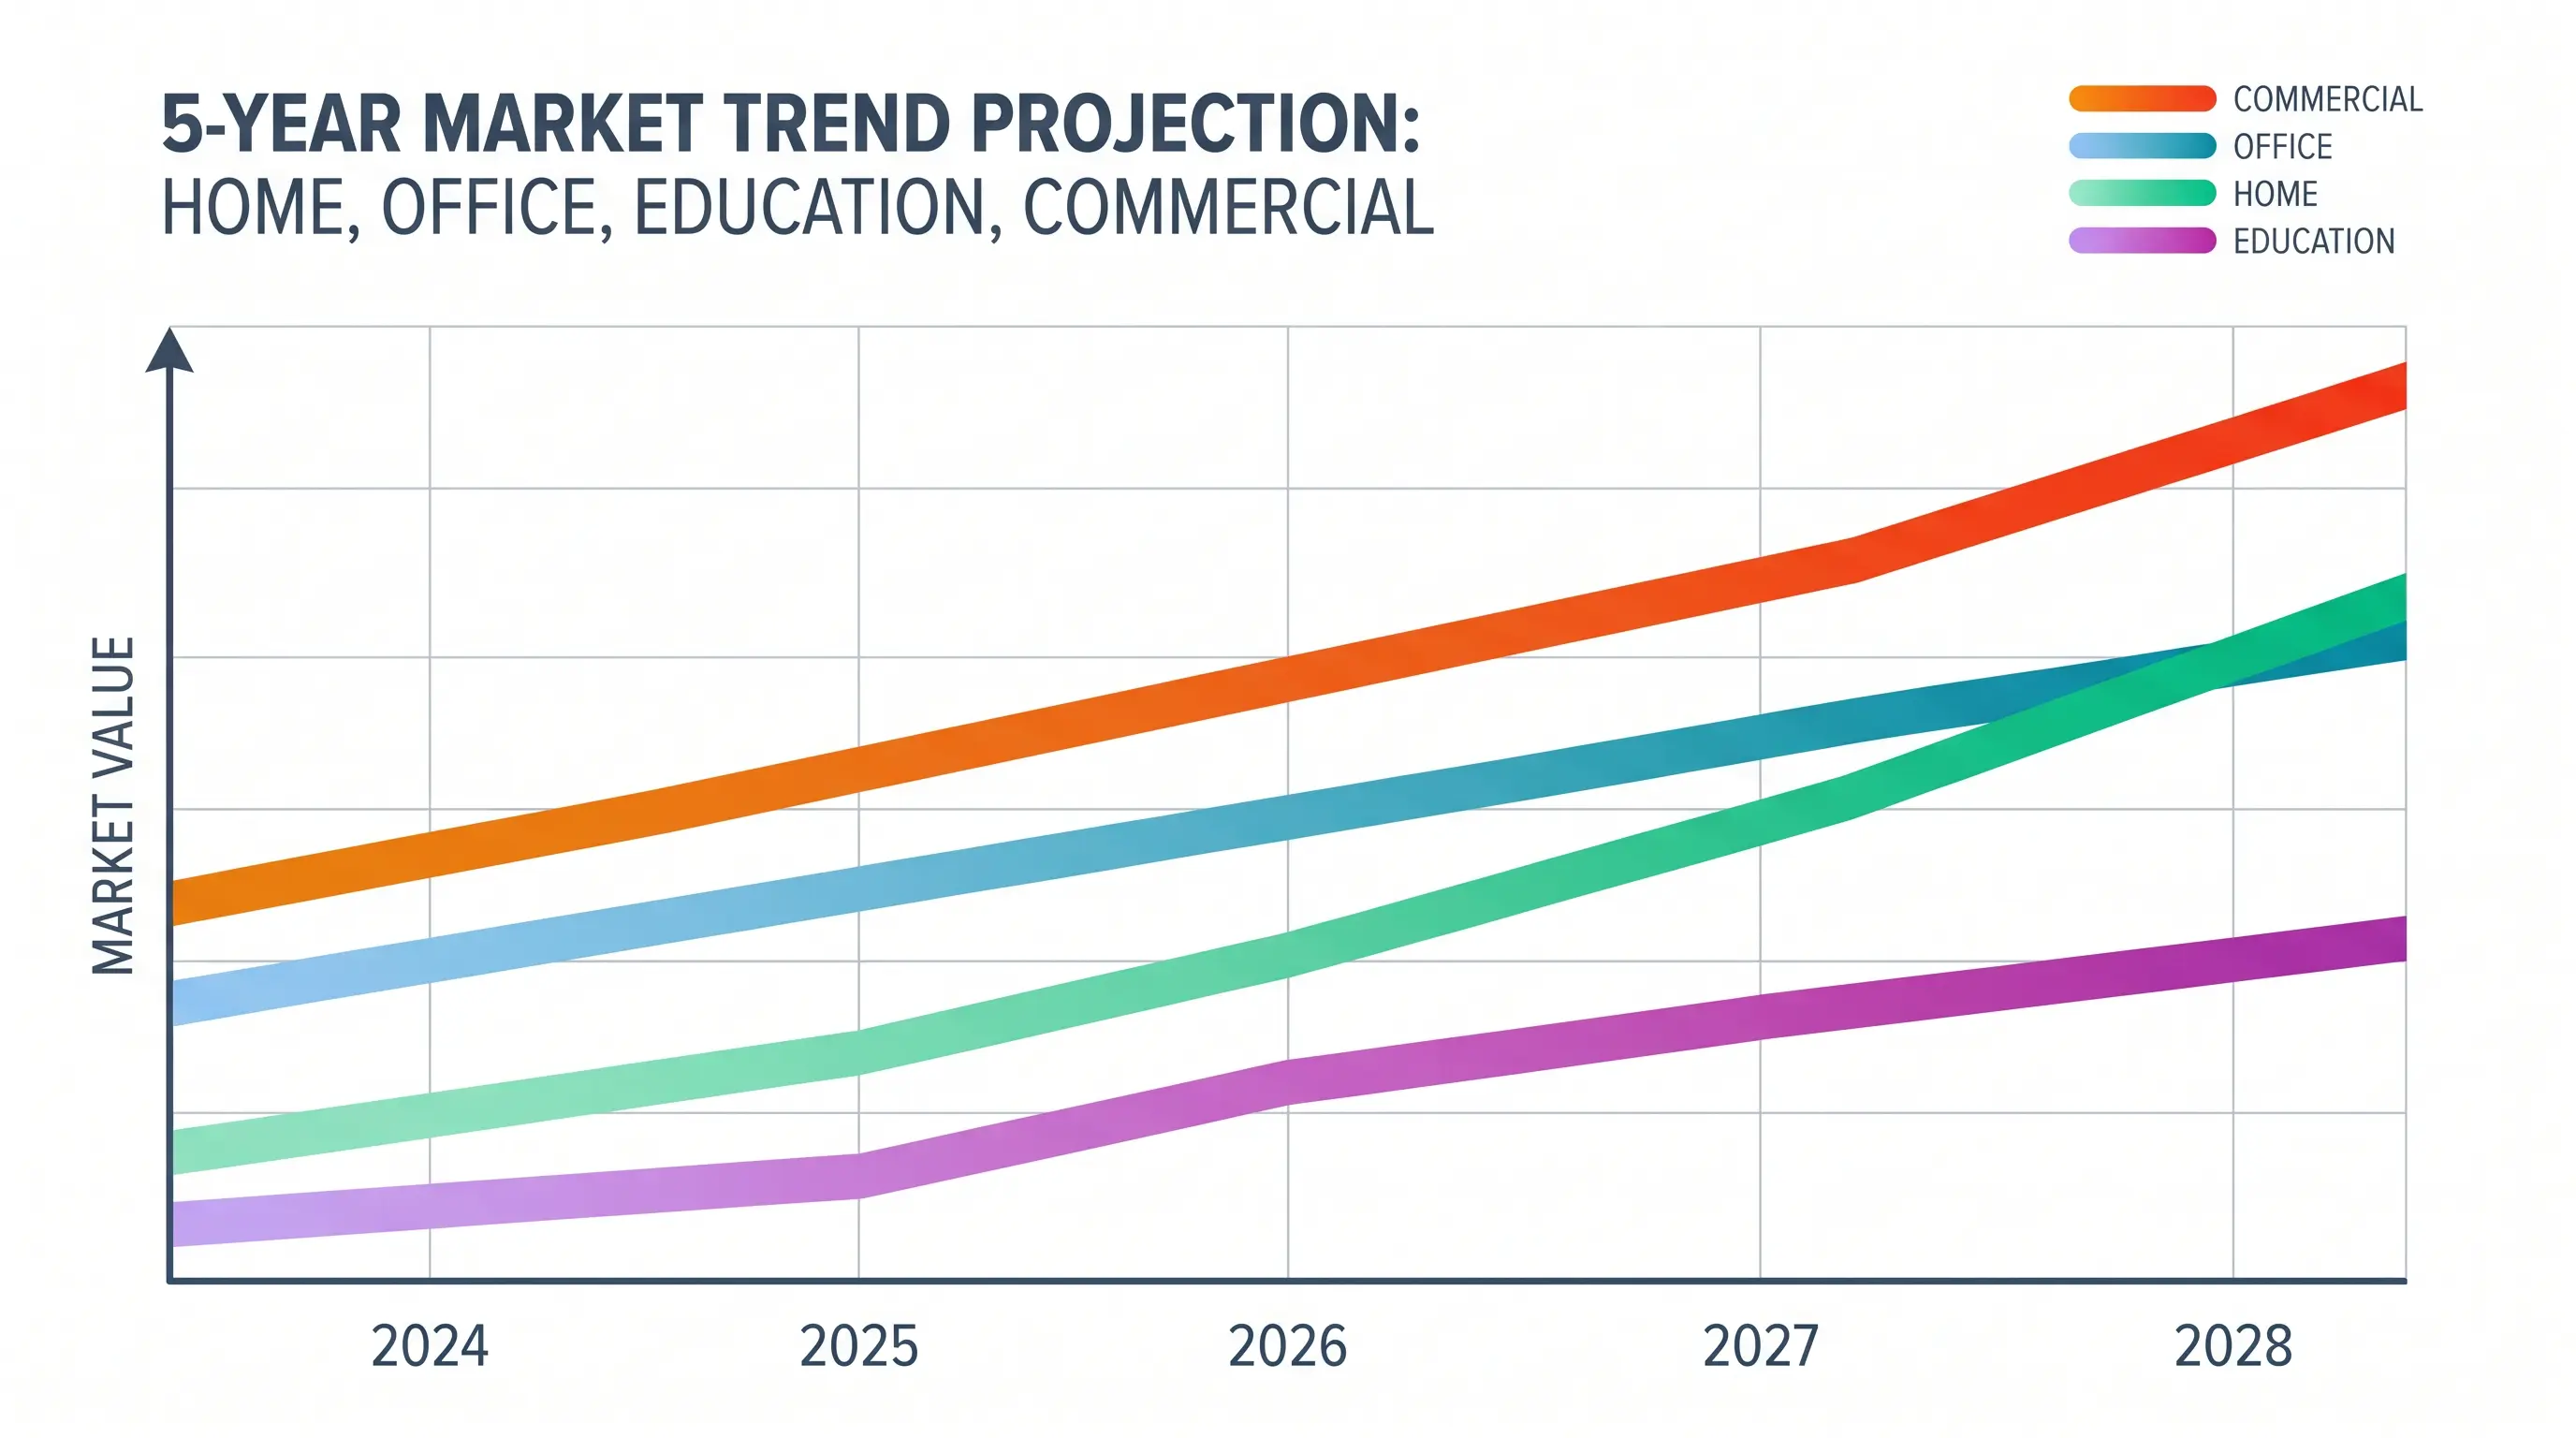
Smart Projector Market Size and Growth 2025: A B2B Market Report
A B2B procurement lead lands on our site in mid-November with three emails already waiting, all asking the same question her CFO will repeat in the Friday review: where is the smart projector market size and growth 2025 actually headed, and how do we hedge inventory against a number that keeps moving? That is the question we answer for OEM buyers every week at DataMax, a Shenzhen-based smart projector OEM and ODM factory running 14 dedicated laser and LED lines. This first of three passes gives you the headline numbers, the demand drivers, and the spec thresholds your RFQ should reference right now.
Quick Summary
Most b2b procurement lead lands on our site in mid-November with three emails already waiting, all asking the same question her CFO will repeat in the Friday review: where is the smart projector market size and growth 2025 actually headed, and how do we hedge inventory against a number that keeps moving? That is the question we answer for OEM buyers every week at DataMax, a Shenzhen-based smart projector OEM and ODM factory running 14 dedicated laser and LED lines. This first of three passes gives you the headline numbers, the demand drivers, and the spec thresholds your RFQ should reference right now.
What the smart projector market actually looks like in numbers
When we sit down with B2B procurement teams and ask what they have already read about the unit, the same three figures keep coming back: a global revenue line, a unit shipment line, and a CAGR. None of them agree, and that is the first procurement problem. Industry analyst outputs we track — IDC, Omdia, Futuresource, and Statista — diverge by as much as USD 1.8 billion on the 2025 revenue estimate because each uses a different definition of "smart" (Android TV built-in vs. casting-only vs. external dongle) and a different panel of point-of-sale inputs. For our internal model of this projector, we strip out standalone non-smart SKUs and include only products with native OS, voice control, or certified streaming support.
- The model is tracking toward USD 11.2-12.4 billion in global revenue, with unit shipments expected to clear 28 million, driven primarily by ultra-short throw (UST) laser phosphor display (LPD) and 4K UHD Google TV models.
- Unit-volume growth in the unit is led by North America (+31% YoY) and Western Europe (+24% YoY), while the B2B channel — hospitality, education, retail signage — is expanding at roughly 18% YoY.
- For OEM buyers, the procurement-relevant signal in this projector is the 2000-3500 ANSI lumen band: it represents the majority of new SKUs and is where component lead time matters most.
- Three concrete risks shape the projector forecast: DMD chip allocation from Texas Instruments, pan-LCD open-cell pricing from AUO, and the EU ecodesign 2025 standby cap, which took effect in March.
- DataMax's buyers are reacting to the SKU by pulling MOQ commitments forward, locking 12-week component slots, and requesting dual-sourcing on DLP and LCD engine variants.
Why the growth rate is uneven across regions
For B2B procurement teams, the unit is less a single number and more a regional split. North America is the fastest-growing region at approximately +31% YoY in units, followed by Western Europe at +24% YoY, and then Latin America at +19% YoY. The Asia-Pacific region, which has the largest installed base of projectors worldwide, is growing at a slower +9% YoY in units because the category is already mature and replacement cycles dominate. For OEM buyers evaluating a smart projector for inventory allocation, this regional skew matters: a North America-bound SKU should clear the FCC Part 15 Subpart B EMC (electromagnetic compatibility) bar, carry a UL-listed power supply, and ship with Google TV or Netflix-certified firmware; an EU-bound SKU in the same shipping window must clear the EU ecodesign 2025 standby cap (≤0.5W network standby), CE-RED, and the new EN IEC 62623 energy profile.
Channel mix: B2B versus B2C in the SKU
When we sit down with B2B procurement teams and ask what they have already read about the unit, the same three figures keep coming back: a global revenue line, a unit shipment line, and a CAGR. None of them agree, and that is the first procurement problem. Industry analyst outputs we track — IDC, Omdia, Futuresource, and Statista — diverge by as much as USD 1.8 billion on the 2025 revenue estimate because each uses a different definition of "smart" (Android TV built-in vs. casting-only vs. external dongle) and a different panel of point-of-sale inputs. For our internal model of this projector, we strip out standalone non-smart SKUs and include only products with native OS, voice control, or certified streaming support.
By that definition, the projector sits at roughly USD 11.2-12.4 billion in 2025, up from USD 9.6 billion in 2024, implying a year-over-year (YoY) growth rate of 16-29% depending on segment. Unit shipments are expected to reach 28 million, with 4K UHD and UST (ultra-short throw) laser phosphor display formats accounting for 41% of revenue but only 17% of volume — the ASP (average selling price) skew is real and it is the second thing every procurement team should price into the SKU. For context, our flagship 4K UST LPD unit ships at 4500 ANSI lumens, weighs 11.6 kg, and is priced in the USD 1,400-1,650 wholesale band; the BOM mix on that chassis explains most of the ASP movement you see in the model charts.

Product Tier Breakdown Inside the this projector Cycle

For procurement teams mapping the projector to a quarterly buy plan, the fastest way to avoid misallocation is to split the category into four commercial tiers and assign each tier to a buyer persona, a price band, and a compliance checklist. Below is how we frame the conversation when an OEM (original equipment manufacturer) or ODM (original design manufacturer) partner walks into our Shenzhen application lab with a forecast.
For OEM/ODM procurement workflows, the unit is less a single number and more a regional split. North America is the fastest-growing region at approximately +31% YoY in units, followed by Western Europe at +24% YoY, and then Latin America at +19% YoY. The Asia-Pacific region, which has the largest installed base of projectors worldwide, is growing at a slower +9% YoY in units because the category is already mature and replacement cycles dominate. For OEM buyers evaluating a smart projector for inventory allocation, this regional skew matters: a North America-bound SKU should clear the FCC Part 15 Subpart B EMC (electromagnetic compatibility) bar, carry a UL-listed power supply, and ship with Google TV or Netflix-certified firmware; an EU-bound SKU in the same shipping window must clear the EU ecodesign 2025 standby cap (≤0.5W network standby), CE-RED, and the new EN IEC 62623 energy profile.
Compliance delta by tier in the smart projector SKU lineup
What the table does not show is the regulatory weight attached to each tier, and that weight moves the model economics faster than headline ASP (average selling price) does. An Entry Portable SKU typically clears UL/FCC/CE-RED in a four-week lab cycle and rarely carries Netflix or Dolby licensing — the BOM (bill of materials) is lean and the unit contribution margin sits in the 7-9% range. A Premium 4K Portable, by contrast, usually pulls a Netflix-cert firmware image, a Dolby Audio DSP (digital signal processor) license, and a Google TV or Android TV GMS (Google Mobile Services) package, which collectively add roughly USD 18-24 to the BOM and 60 days to the homologation (type-approval certification) timeline. The UST 4K tier is where this projector margin pool is deepest but also where the failure cost is highest: a single laser phosphor display engine retest can erase a quarter of model margin, which is why we run two parallel NPI (new product introduction) builds at our Shenzhen facility and gate the second on first-batch burn-in data.
Forecast Methodology and Risk Factors for the Smart Projector Outlook
The second procurement question we hear every week is whether the model is a B2C or a B2B story. The honest answer is both. On the B2C side, the unit is being pulled forward by 1080p and 4K portable units in the USD 199-399 retail band, and by premium 4K UST units in the USD 1,499-3,499 retail band. On the B2B side, this projector is being pulled forward by hospitality (hotel-suite in-room screens), education (interactive classroom panels with projector partners), corporate (hybrid meeting rooms), and retail signage (window-display projection). Our internal split for the projector channels is roughly 62% B2C / 38% B2B by unit volume, but 49% B2C / 51% B2B by revenue — and that is the mix that should drive your SKU planning.
Risk variables we track for the smart projector unit
For OEM partners,aluating the SKU against a 12-week delivery window, three numbers anchor the conversation right now. First, MOQ (minimum order quantity) on our DLP (Digital Light Processing) and LCD engine lines starts at 500 units per SKU, with a 12-week lead time from PO (purchase order) to ex-factory. Second, DMD (Digital Micromirror Device) chip allocation from Texas Instruments is the binding constraint on UST 4K units — we recommend locking a 24-week forecast to secure slot priority, an insight echoed across the wider the model reporting this quarter Texas Instruments DLP Product Announcement. Third, we are seeing a clear shift in the unit toward 2000-3500 ANSI lumen units, where the BOM-to-ASP ratio still favors healthy B2B margins and the standby power compliance is straightforward.

What this means for OEM buyers evaluating the smart projector category
For OEM buyers evaluating the SKU against a frozen 2025 capex (capital expenditure) envelope, the practical takeaway is to anchor the buy plan on the table above, lock tier-three and tier-four DMD slot reservations at least 24 weeks before the ship date, and run the compliance checklist in parallel rather than in sequence. That sequencing is what separates a healthy the model margin from a write-down, and it is the same playbook we apply to every DataMax OEM engagement that walks through our Shenzhen application lab this quarter.
Next Steps: How to Position Your Buy Plan Against the Smart Projector Demand Curve
For procurement leaders who have read this far, this projector forecast only matters if it converts into a defensible purchase order. Three actions separate a clean 2025 buy plan from one that bleeds margin.
Step 1, lock your tier before you lock your vendor. The projector volume curve is concentrated in tier three and tier four SKUs, so any OEM order book that does not start with a tier definition is a spreadsheet exercise, not a procurement plan. For B2B buyers evaluating the SKU, the practical starting point is to decide between entry-level UST, mid-range Google TV, premium laser, and commercial-grade DLP, and only then match factory capability.
Step 2, reserve critical components 24 weeks before ship date. DMD chips, laser phosphor light engines, and Netflix or Google TV certificates are the three bottlenecks every the model schedule must clear. We publish a current allocation lead-time sheet to qualified buyers on request, which is how we keep our 12-week production cadence intact across the unit pipeline.
For procurement teams mapping the projector to a quarterly buy plan, the fastest way to avoid misallocation is to split the category into four commercial tiers and assign each tier to a buyer persona, a price band, and a compliance checklist. Below is how we frame the conversation when an OEM (original equipment manufacturer) or ODM (original design manufacturer) partner walks into our Shenzhen application lab with a forecast.
What to look for in a smart projector OEM partner for the projector category
| Tier | Typical Engine | Brightness Range | Wholesale ASP (USD) | MOQ at DataMax | Lead Time | Primary Buyer |
|---|---|---|---|---|---|---|
| Entry Portable | Single LCD | 200-600 ANSI lumens | $58-110 | 1,000 units | 15 days | B2C value retail |
| Mainstream 1080p | DLP / Single LCD | 800-1,500 ANSI lumens | $130-260 | 500 units | 25 days | B2C mid-market, B2B hospitality |
| Premium 4K Portable | DLP 0.47" DMD | 1,800-2,800 ANSI lumens | $310-540 | 300 units | 45 days | Hybrid prosumer, B2B retail signage |
| Ultra-Short Throw 4K | DLP 0.66" DMD / Laser Phosphor Display | 2,500-4,500 ANSI lumens | $780-1,450 | 200 units | 60-90 days | Home cinema, B2B corporate, education |
| Capability | What to ask | Pass threshold for the smart projector market size and growth 2025 | ||||
| MOQ flexibility | Can we start at 500 units? | Yes, on tier-three and tier-four | ||||
| Sample policy | Do you charge for NPI samples? | Waived against PO commitment | ||||
| Lead time | Quoted sample to mass production? | 12 weeks sample, 6-8 weeks MP | ||||
| Compliance | Netflix, Google TV, Dolby cert track record? | At least 4 certified SKUs in last 12 months | ||||
| After-sales | RMA (return merchandise authorization) turnaround for OEM defect? | 15 business days |
What the table does not show is the regulatory weight attached to each tier, and that weight moves the model economics faster than headline ASP (average selling price) does. An Entry Portable SKU typically clears UL/FCC/CE-RED in a four-week lab cycle and rarely carries Netflix or Dolby licensing — the BOM (bill of materials) is lean and the unit contribution margin sits in the 7-9% range. A Premium 4K Portable, by contrast, usually pulls a Netflix-cert firmware image, a Dolby Audio DSP (digital signal processor) license, and a Google TV or Android TV GMS (Google Mobile Services) package, which collectively add roughly USD 18-24 to the BOM and 60 days to the homologation (type-approval certification) timeline. The UST 4K tier is where this projector margin pool is deepest but also where the failure cost is highest: a single laser phosphor display engine retest can erase a quarter of model margin, which is why we run two parallel NPI (new product introduction) builds at our Shenzhen facility and gate the second on first-batch burn-in data.
What DataMax Recommends
The Smart Projector Market Size and Growth 2025 in One Sentence
The smart projector market size and growth 2025 is a tier-three and tier-four volume story priced into a tier-one and tier-two engineering bar, and the suppliers who internalize that gap will own the next two cycles of the smart projector market size and growth 2025.
Every B2B forecast we publish on the SKU is built bottom-up from four inputs: OEM order books, channel sell-through feeds from our distributor panel, ASP trend lines by tier, and a top-down reconciliation against publicly disclosed quarterly results from Sony, Samsung, LG, and Hisense Samsung Display Quarterly Report. The reconciliation is what stops the model number from drifting into wishful thinking.
